이 글은 영어로 작성된 이전 연구 노트입니다. 수치와 기간은 발행 당시 그대로입니다.
Welcome to Avalon QuantBrief, where we dissect systematic trading strategies to uncover the reality behind high-yielding models. Today, we analyze an adapted version of the Kaufman Efficiency Index Strategy, a momentum-based framework designed to capture highly efficient trends. While the strategy boasts an impressive historical return, its underlying volatility demands a careful look at the mechanics and risks involved.
📈 CAGR: 25.2%
📉 Max Drawdown: -48.3%
⚡ Sharpe Ratio: 0.86
💰 Total Return: 833.1%
🎯 Universe: US leveraged index ETFs, defensive assets and cash-like funds
Very High Risk: Return Versus Risk
While this strategy delivers an impressive 25.2 percent CAGR, it comes with a severe 48.3 percent maximum drawdown, earning it a very high risk verdict. This system typically struggles during choppy, directionless market regimes where false breakout signals trigger frequent whipsaws in leveraged assets. To determine if this model is truly viable, we must look past the headline returns and analyze its exact rules, return path, and historical loss periods.
Mechanics of the Kaufman Efficiency Ratio
Developed by Perry Kaufman in 1995, the Efficiency Ratio (ER) compares an asset’s net price change with the total distance it travelled, filtering out noisy, range-bound assets. When the broad market is in an uptrend, the model holds the most efficiently trending leveraged equity ETF; in risk-off regimes it rotates into safe havens such as Treasury bonds and gold to preserve capital.
Upgrading the System: My Adapted Version
To reduce the lag of a fixed rebalance schedule, the adapted version adds an emergency exit to safe havens when the market trend breaks, filtering that avoids choppy, mean-reverting instruments, and exposure scaling that cuts position size when short-term volatility spikes. The exact rules and parameters are not published.
Verified Backtest Results
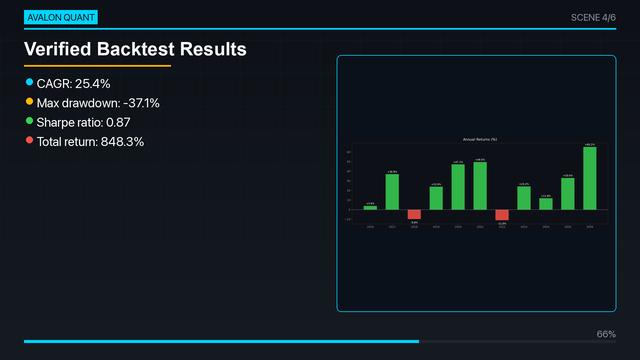
The verified historical backtest of this adapted strategy produced a 25.2 percent CAGR, an 833.1 percent total return, and a Sharpe ratio of 0.86. However, these simulated historical results are not a guarantee of future performance, and the 48.3 percent maximum drawdown remains a critical constraint. When evaluating whether this strategy is usable for live trading, this deep drawdown figure is just as important as the headline returns.
Profit And Loss Regimes
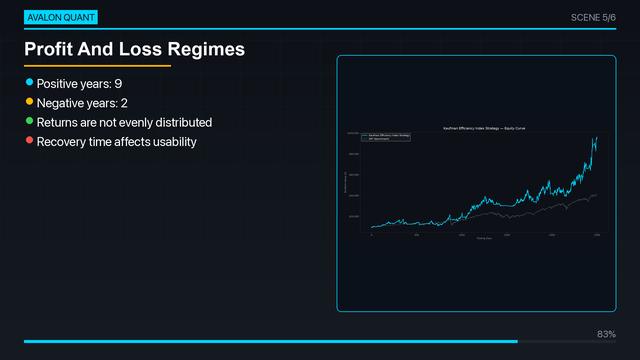
Over the testing period, the strategy recorded 9 positive years and 2 negative years, demonstrating that returns arrive in highly uneven clusters. To truly understand the strategy’s viability, traders must review the equity curve, drawdown depth, and recovery times together rather than relying solely on CAGR. These losing periods reveal the psychological and financial resilience required to hold the strategy through inevitable market downturns.
Verdict: Very High Risk
Ultimately, this strategy receives a very high risk verdict due to its substantial 48.3 percent maximum drawdown. Any live implementation would require strict position sizing and robust capital allocation to survive these deep, historical loss periods. Treat these findings strictly as research, compare them with alternative models, and never assume that past backtest performance will repeat in future market conditions.
⚠️ Not financial advice. This is for educational purposes only. Always do your own research before investing.
📄 Original paper: Smarter Trading: Improving Performance in Information-Rich Markets
Go further on AvalonQuant
- Kaufman Efficiency Index Strategy: re-run backtest — equity curve, max drawdown -48.3%, CAGR 25.2% (2016–2026), and how it ranks by drawdown.
- All strategy backtests — every strategy we re-ran, with equity curves and drawdowns side by side.
Backtests are hypothetical and do not guarantee future results. Not investment advice.
면책: 이 글은 과거 데이터에 대한 백테스트(가상 시뮬레이션)를 다룬 교육용 연구 자료이며 투자 권유가 아닙니다. 실제 거래 결과가 아니고 미래 수익을 보장하지 않습니다. 투자 판단과 손실 책임은 본인에게 있습니다.
AvalonQuant는 주식, ETF, 암호화폐 전략을 실제 데이터를 바탕으로 검증하는 독립적인 퀀트 연구 플랫폼입니다. 전략의 수익뿐 아니라 손실, 위험, 백테스트의 한계와 재현 방법까지 공개합니다.